Ever thought about starting your own "bank"? It can be a clever move for medium-sized businesses, too! Companies establishing their own "bank" in the form of a lump-sum-funded support fund (pdUK) has a long tradition. Legally speaking, it isn't a "bank," of course, but from a business perspective, it certainly functions like one. That is why the pdUK is also called an "entrepreneur bank," and it was originally an instrument used by large-scale industry for company pension schemes. However, this model can also make sense for SMEs with as few as 10 employees. If a company decides to start its own "bank," it brings many benefits to the workforce—and to the company itself. That is why it is becoming increasingly popular among medium-sized enterprises.
How employees benefit from the pdUK
Today, company pension schemes offered by banks and insurance companies are often burdened by poor returns. In this form, retirement provision has lost much of its appeal. With an entrepreneur bank, however, medium-sized companies can offer their employees an attractive company pension model:
• Employees get more out of it: Since the employer covers all costs and the contributions paid in are not reduced by additional fees, employees benefit from attractive returns.
• The company is free to choose the interest rate. Consequently, the interest can be higher than that offered by insurance companies.
• The pension model is transparent and easy to calculate.
• The Pension Security Association (Pensionssicherungsverein) protects employees in the event that a company cannot meet its obligations due to business difficulties. Thus, the pdUK is also insolvency-proof.
• The pdUK has a positive effect on employee motivation, as the company makes an active contribution to retirement provision and helps close the pension gap.
How the company benefits from the pdUK
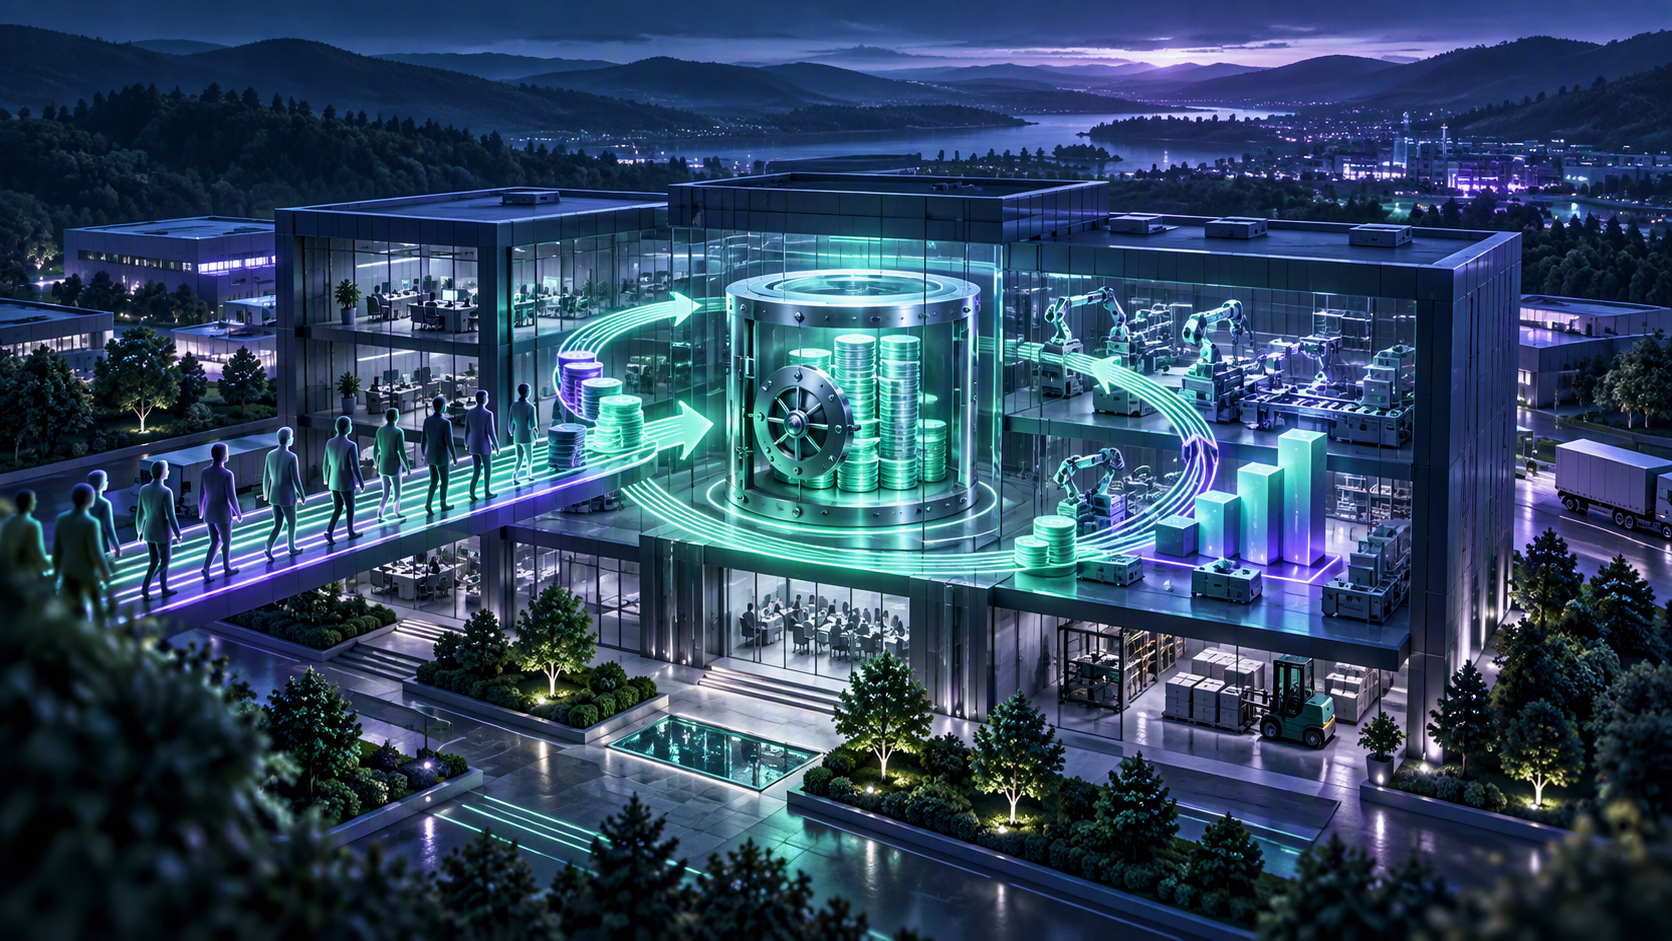
When a company establishes an entrepreneur bank, it foregoes the involvement of banks and insurance companies. The entrepreneur bank is subject to strict regulations, must be managed in accordance with the law, and is subject to regular audits. But how does such an entrepreneur bank actually work? It’s quite simple: contributions for the company pension scheme are deducted from the employee's gross salary and are not subject to income tax or social security contributions. The employer adds their employer contribution without any deductions for the employee. This means that money that would have left the company in a standard pension scheme remains within the company's sphere of influence. This creates interesting opportunities for the company and the entrepreneur:
• The company can receive a loan from the support fund. This can reduce the need to take out external financing from banks, which can lead to interest rate advantages.
• Growth and investments can be financed independently of banks and on a long-term basis. The company's economic resilience is strengthened.
• The pdUK scores points with low setup and closing costs.
• Expenses for the pdUK are operating expenses and reduce taxable profit.
• The pdUK is an excellent tool for retaining and attracting employees.
Bottom line: All in all, an entrepreneur bank makes a medium-sized company more robust and gradually expands its financial flexibility. It contributes to employer attractiveness and can be a truly compelling point when it comes to employee retention or recruitment. THE MAK`ED TEAM has many years of experience in implementing entrepreneur banks and is a cooperation partner of Authent, a renowned professional provider of support funds. We at THE MAK`ED TEAM know how to customize the flexible parameters of the entrepreneur bank so that the pdUK brings the desired benefits to the company. In collaboration with Authent, we also ensure our services are on solid ground in terms of tax, law, and financial mathematics. This gives a medium-sized company that chooses the pdUK the certainty that the potential of an entrepreneur bank is fully utilized for both the company itself and its employees.